A resource for those seeking information on organizing and transforming spaces.
Your Roadmap to a More Secure, Comfortable, and Well-Planned Future
Planning your financial future involves more than saving money. You need to picture your ideal daily life and set steps to reach it. Without a clear path, you risk running short on funds or missing experiences that matter most.
Planning your financial future involves more than saving money. You need to picture your ideal daily life and set steps to reach it. Without a clear path, you risk running short on funds or missing experiences that matter most.
In this guide, you will learn how to:
• Picture your dream lifestyle and set clear priorities
• Assess your net worth along with income and expenses
• Establish SMART goals for short-, mid-, and long-term plans
• Create a savings and investment strategy that balances growth and safety
• Protect your assets with insurance, wills, and trusts
• Keep yourself healthy and engaged through fitness and community
• Budget for travel, hobbies, and special projects
• Leverage apps and online tools for real-time planning
Whether you are just starting your career or preparing for the next phase of life, this roadmap provides a step-by-step plan for planning your financial future with confidence and peace of mind.
Let us begin by envisioning where you want to live and how you want to spend your days in retirement.
Setting Your Retirement Destination
Planning retirement starts with picturing life after work. Envision where you live, how you spend your days, and which aspirations drive your joy. Use tools like vision boards or lifestyle mapping to capture ideas and keep goals in focus.
Envisioning your ideal lifestyle
Consider travel aspirations, hobbies, and time with loved ones. Ask yourself:
• Which destinations or bucket-list trips matter most?
• Do you see yourself downsizing or moving to a retirement community?
• How much family time and personal projects do you want each week?
Visualizing daily routines and special milestones creates a clear picture of your future.
Identifying priorities and values
Next, rank what matters most, such as health, adventure, or legacy. Factor in your timeframe for retiring in 10, 20, or 30 years to shape savings targets. Evaluate cost of living, local amenities, and proximity to family.
Aligning your core values with concrete goals ensures your roadmap reflects the lifestyle you desire. Also, consider local infrastructure such as reliable HVAC services, property maintenance, and utility costs when picking a home that supports your comfort.
Assessing Your Financial Starting Point
Before planning your financial future, establish a clear view of your current finances. This section shows how to measure net worth and track income and expenses. Knowing where you stand helps you plan with confidence. It also guides your next steps in saving and investing.
Net Worth Calculation
Listing Your Assets
• Cash and checking or savings balances
• Investments such as stocks and bonds
• Real estate or property values
• Vehicles and other valuable items
Listing Your Liabilities
• Mortgage balances
• Auto and student loans
• Credit card debt
• Other personal loans
Computing Your Net Worth
Subtract total liabilities from total assets. A positive net worth means assets exceed debts. A negative net worth highlights areas for improvement. Review these figures at least once a year to spot major shifts in your financial health.
Income and Expense Tracking
Start by identifying all income streams, such as salaries, rental income, or freelance work. Review bank and credit card records to capture every payment.
Categorizing Expenses
• Fixed costs (rent, utilities)
• Variable costs (groceries, entertainment)
• Recurring fees (subscriptions)
• Non-monthly expenses (insurance premiums)
Calculating Net Cash Flow
Subtract total monthly expenses from total monthly income. A surplus shows spare funds for saving or investing. A shortfall signals a need to adjust spending. Regularly update these numbers to keep your plan on track.
Next, use this baseline to set measurable goals and track growth.
Goal Setting: Short-, Mid-, & Long-Term Milestones
As part of planning your financial future, set clear milestones to track progress across different horizons. By applying SMART criteria, you ensure each goal stays focused and achievable.
SMART Financial Goals
Define goals that are Specific, Measurable, Achievable, Relevant, and Time-bound.
• Specific: e.g., save $5,000 for an emergency fund
• Measurable: track monthly contributions
• Achievable: align with income and expenses
• Relevant: focus on priorities like debt reduction
• Time-bound: set a deadline, such as 12 months
This framework applies to short-, mid-, and long-term objectives.
Timeline Planning
Use a visual timeline to assign each milestone a clear date. Break your objectives by horizon:
1. Short-term (0–12 months): build an emergency buffer, pay off high-interest debt
2. Mid-term (1–5 years): save for a home down payment, invest in retirement accounts
3. Long-term (5+ years): plan for college funds, secure retirement income
Map these milestones on a calendar. Review progress quarterly and adjust targets as needed. Celebrating small wins keeps motivation high and ensures your roadmap stays on course.
Building Your Financial Roadmap
In planning your financial future, laying out a clear path helps you save, invest, and leverage retirement accounts for long-term security. Focus on building habits that balance liquidity, growth, and tax efficiency.
Savings Strategies
Start by tracking income and expenses to ensure you spend less than you earn. Key steps:
• Automate deposits into a high-yield savings or money market account
• Build an emergency fund equal to 3–6 months of living expenses
• Implement a debt reduction plan targeting high-interest loans first
Investment Options
Align your portfolio with your risk tolerance and timeline. Consider:
• A mix of stocks, bonds, and real estate for balanced growth
• Dollar-cost averaging into low-cost index funds or ETFs
• Regular rebalancing to maintain diversification across asset classes
Retirement Account Optimization
Maximize Employer Match
Contribute at least enough to your 401(k) to capture any employer match.
Choose the Right Account
• Compare Roth vs Traditional IRAs based on current and future tax brackets
• Use catch-up contributions if you are 50 or older to boost savings
Tax Planning Strategies
Use deductions, credits, and account selection to minimize tax liability and enhance long-term growth.
Health & Wellness Roadmap
Maintaining health supports long-term vitality. Combine fitness routines, balanced nutrition, and community engagement for sustained well-being.
Physical Fitness and Nutrition
Aim for at least 150 minutes of moderate aerobic activity or 75 minutes of vigorous exercise each week. Complement cardio with strength training two days weekly to preserve muscle mass and bone density.
Follow a balanced eating plan rich in vegetables, fruits, whole grains, lean proteins, and healthy fats. Consider a Mediterranean-style diet to support metabolic health and reduce inflammation. Use meal planning or macro tracking to maintain consistent energy levels.
Mental Health and Social Connections
Integrate daily mindfulness practices such as guided breathing or brief meditation to build stress resilience. Prioritize sleep by setting a consistent bedtime routine.
Engage with community through clubs, volunteering, or group classes to foster social bonds. Cultivate close relationships by scheduling regular catch-ups with friends and family. Pursue lifelong learning and purposeful hobbies to boost mood and cognitive function.
Estate Planning & Insurance Essentials
Effective estate planning protects assets and ensures your legacy follows your wishes. It combines legal tools and insurance to safeguard your family’s future.
Wills and trusts
A will provides clear instructions for distributing property and naming guardians for minor children. Trusts can avoid probate court, streamline asset transfer, and allow conditions like age-based distributions.
A revocable living trust offers flexibility and privacy during your lifetime. An irrevocable trust may shield assets from creditors and reduce estate taxes.
Powers of attorney
Designate a durable power of attorney to manage finances if you become incapacitated. A health care power of attorney or living will spells out medical preferences and appoints someone to make treatment decisions.
Life and health insurance planning
Life insurance policies pay benefits directly to named beneficiaries. Regularly review coverage amounts and designations after major events.
Long-term care insurance can protect savings by covering costs of assisted living or nursing care. These strategies work together to preserve estate value and support family needs.
Budgeting for Experiences and Lifestyle
Allocating funds for new pursuits needs a clear plan. Budget for travel, hobbies, and dining with simple frameworks.
Travel and Hobbies Budgeting
Divide your discretionary fun money into core categories:
• Travel: annualize your monthly allotment (example: $300 × 12 = $3,600 per year)
• Hobbies: estimate cost per hour and equipment depreciation
• Dining and entertainment
Adjust overall allocation based on your financial phase:
• 25% of after-tax income if you have a fully funded emergency fund
• 20% if you are building that safety net
• 10% if you are prioritizing debt payoff
Employ rollover budgets to carry unused funds into future months.
Hidden Costs and Contingency Funds
Create a miscellaneous buffer for variable fees, incidental travel charges, and hobby supplies. Add a 5–10% contingency on top of core budgets to cover exchange-rate fluctuations or unexpected expenses. Keep these reserves separate to avoid derailing your planned experiences.
Leveraging Digital Tools and Innovative Resources
Online calculators and robo-advisors simplify planning with real-time projections and automated portfolios. Integrating these tools can cut manual work and keep your goals on track.
Retirement planning calculators
• Vanguard’s calculator offers quick, no-login retirement estimates
• Fidelity’s Planning & Guidance Center generates readiness scores and printable reports
• PopaDex tracks net worth across currencies and projects FIRE timelines
Robo-advisors and apps
• Wealthfront: diversified portfolios and tax-loss harvesting (0.25% fee, $500 min)
• Fidelity Go: no fees under $25,000 and advisor support
• Schwab Intelligent Portfolios: no management fee and $5,000 min
Conclusion
Building a secure, comfortable, and well-planned future is within reach when you follow a clear roadmap. By envisioning your ideal lifestyle, assessing your finances, and setting SMART goals, you lay the foundation for lasting confidence.
You have the tools to save, invest, protect your assets, and enjoy life to the fullest.
Key takeaways:
• Clarify your vision and align goals with your values
• Calculate net worth and track income versus expenses
• Set specific, measurable, achievable, relevant, and time-bound milestones
• Balance savings, investments, tax planning, and insurance
• Maintain physical fitness, mental wellness, and social connections
• Establish wills, trusts, and powers of attorney to protect your estate
• Budget for travel, hobbies, and unexpected costs with contingency funds
• Use calculators, robo-advisors, and apps to monitor progress in real time
This guide provides a step-by-step plan and the resources you need. Now it is time to take action. Choose one milestone, schedule a planning session, or download a budgeting app today. Consistent steps lead to lasting results.
Your roadmap is set. Move forward with confidence and build the future you imagine.
Sara Young
Sarah Young holds a Bachelor's in Marketing Communications from California Lutheran University. She enjoys running her website glitternglue.com, where she can share her own and others' thoughts on lifestyle tips! During her spare time, she enjoys going to the beach with her dog or painting nature murals.
Is Downsizing Right for You? Signs It’s Time to Sell Fast
Deciding to downsize is a big life shift, and it can feel emotional, practical, and financial all at once. Many homeowners wait longer than they need to because they feel unsure about timing. Others know they’re ready but don’t know how to read the signs. Downsizing doesn’t always mean something negative; in many cases, it opens new doors, eases stress, and improves daily comfort. If you’re wondering whether the moment has arrived, this guide walks through clear signs that moving to a smaller, more manageable home might make life easier. You’ll also see when selling fast becomes the smartest option.
We partnered with a real estate company for this post. The opinions in the post are honest. All reviews and opinions expressed in this post are based on our personal views. We are excited because we know you will love it.
Deciding to downsize is a big life shift, and it can feel emotional, practical, and financial all at once. Many homeowners wait longer than they need to because they feel unsure about timing. Others know they’re ready but don’t know how to read the signs. Downsizing doesn’t always mean something negative; in many cases, it opens new doors, eases stress, and improves daily comfort. If you’re wondering whether the moment has arrived, this guide walks through clear signs that moving to a smaller, more manageable home might make life easier. You’ll also see when selling fast becomes the smartest option.
When Your Home Demands More Than You Can Give
For many people, the first hint comes from the house itself. A property that once felt comfortable gradually becomes a drain on time, energy, and money. Homes age, and the workload grows with them. Constant repair lists, rising utility costs, and yard upkeep can turn weekends into chores instead of rest. If you catch yourself saying “I’ll get to that later” more often, it might signal that the home has outgrown your lifestyle.
There are also times when the layout no longer fits the way you live. Large unused rooms, stairs that feel tough to climb, or storage spaces packed with things you don’t use all reflect a shift. When your home stops supporting your daily comfort, the idea of selling gets clearer. If you decide a quick, simple sale fits your situation, Salt & Light Property Solutions is often the kind of service homeowners turn to for fast and convenient options.
Feeling Financial Pressure From Your Property
Money doesn’t need to be the only reason to downsize, though it definitely plays a part for many homeowners. Once easy mortgage payments may feel tight due to changes in income or rising expenses. A larger home usually comes with higher taxes, insurance, and maintenance costs, and those numbers add up month after month.
During certain seasons of life, reducing expenses can bring peace of mind. Lowering bills by downsizing often frees up income for travel, hobbies, savings, or healthcare. Some homeowners also want fewer financial responsibilities as they approach retirement or shift careers. A fast sale can be useful when expenses are building quickly. Instead of waiting months for the traditional market, selling sooner gives you the financial reset you need.
When Your Home Feels Bigger Than Your Life
Sometimes the house becomes too quiet. Children grow up and move out, leaving empty rooms that gather dust. A once-lively home slowly turns into a space filled with memories instead of activity. This emotional shift often surprises people, and they realize the house no longer fits the current rhythm of life.
It’s also common for people to feel weighed down by possessions. Years of accumulated items take up space physically and mentally. Many homeowners describe downsizing as a fresh start, giving them a chance to simplify and create an environment that reflects who they are today.
A smaller home can feel more inviting, easier to clean, and more aligned with what you genuinely use. If you walk through your home and see more unused areas than lived-in spaces, it may be a sign that you’re ready for something cozier.
When Life Changes Faster Than Your House Can Keep Up
Life transitions push many people toward downsizing. A new job in a different city, a shift to remote work, or a desire to be closer to family can all influence the decision. Health considerations also play a role. Mobility challenges or medical needs sometimes make a smaller, one-level home the more practical choice.
There are moments when you simply need flexibility. A faster sale allows you to move forward without long delays or uncertainty. This becomes valuable during unexpected life events when you want less stress on your plate. Downsizing isn’t just a property decision; it’s a lifestyle adjustment. Choosing timing that aligns with your personal life ensures smoother changes overall.
Wanting More Freedom and Less Responsibility
Many homeowners downsize because they want to spend more time living and less time maintaining a property. A large home can tie you down, while a smaller one often opens more room for travel, relaxed weekends, and spontaneous plans. Some people also crave a shift toward experiences rather than belongings. With fewer rooms to worry about, it becomes easier to focus on activities that bring joy. Downsizing often creates that sense of freedom.
A smaller home can also create opportunities for closer communities. Many people enjoy living in walkable neighborhoods, condos with amenities, or areas closer to their favorite places. If your lifestyle goals point toward more convenience, a streamlined home might be exactly what you need.
Signs You Should Consider Selling Fast
A quick sale isn’t always necessary, though certain signs make it the better choice:
1. Repairs Are Stacking Up
If your home needs significant updates you don’t want to do, selling fast can remove the pressure instantly. Many quick-sale buyers take homes as-is, so you don’t need to fix anything.
2. You Need Cash Soon
Financial shifts can require fast access to equity. Selling quickly brings relief without months of listing, showing, and negotiating.
3. You’re Relocating
When a job or personal situation requires a fast move, a quick sale minimizes stress and prevents you from juggling two homes.
4. You Want Less Stress
Sometimes the emotional weight of selling traditionally feels overwhelming. A simple, streamlined path helps you move forward confidently.
A Clearer Path Toward Your Next Chapter
Downsizing is a personal journey, and the right time looks different for every homeowner. The best approach is to pay attention to how your home feels, how your finances look, and how your life is shifting. When your house demands more than it gives, that’s often the moment clarity arrives. Selling fast becomes a helpful option when you want simplicity, speed, and convenience. Whether you seek freedom, financial breathing room, or a home that matches your current lifestyle, downsizing can open the door to a lighter, more comfortable future.
Making the Right Housing Choice for Your Retirement Years
Investing in a retirement home is an important decision that will affect your lifestyle, financial security, and peace of mind. While you may be searching for ways to stay in your current location or seeking other opportunities, there are several factors that will influence your decision-making process.
We partnered with a real estate company for this post. The opinions in the post are honest. All reviews and opinions expressed in this post are based on our personal views. We are excited because we know you will love it.
Investing in a retirement home is an important decision that will affect your lifestyle, financial security, and peace of mind. While you may be searching for ways to stay in your current location or seeking other opportunities, there are several factors that will influence your decision-making process.
Keep reading as this article will explore all you need to know, from factors to consider to pros and cons if you choose to rent or buy a property for retirement.
Factors to Consider When Choosing Your Retirement Home
Where you choose to live in retirement is crucial for your everyday experiences and overall long-term happiness. The following five items will assist you in evaluating prospective living locations and finding a place that best suits your needs.
1. Location and Proximity to Essentials
Consider how far away things that matter to you (family, hospitals, grocery stores, etc.) As we grow older, being near good quality health care is becoming a bigger factor than ever before.
Being able to get around without having to be concerned about getting from point "a" to point "b," and staying in touch with those who provide you emotional support are two big advantages of a conveniently located area.
2. Affordability and Ongoing Costs
Look at all the costs related to the house (or condo) you buy (and rent), as well as any costs for repairs and maintenance. As a homeowner, working with an Arlington property manager gives you access to trusted contractors and cost-effective repairs. With a property manager’s proactive help, you can be ahead of repair costs and other important factors, allowing you to plan early.
3. Maintenance Responsibilities
Be honest with yourself about how much work you are willing to do. With homeownership comes lawn care, leaky faucet fixes, and repairs. When renting, you have passed this responsibility to a landlord.
If you decide to buy, an Arlington property manager can assist with coordinating the maintenance of your home, allowing you to enjoy your new home without having to perform the physical labor to fix it yourself.
4. Accessibility and Aging in Place
Think about whether your house will work for you long-term. Consider a one-level design and include features such as wider doorways, no steps to enter, and bathroom designs that feature grab bars.
By planning, you can ensure you remain as comfortable as possible regardless of your future mobility limitations. It is also less expensive to plan ahead and make smart choices when purchasing a home versus the cost of retrofitting after you move into a new home.
5. Lifestyle and Community Fit
Your retirement home is a place where you can pursue your desired way of life. What type of neighborhood do you envision? Quiet suburban neighborhood? Walkable urban neighborhood? An active community with many opportunities to engage in hobbies and social events?
Your location will have an impact on your overall quality of life and daily experiences. Take time to visit the neighborhoods at different hours of the day to really experience the energy of the area.
Rent or Buy in Retirement: Pros and Cons Explained
Buying a home versus renting has financial implications for you in retirement. However, each choice provides different freedoms and a sense of peace in terms of your evolving lifestyle.
Here are the pros and cons of renting or buying a retirement home:
Pros and Cons of Buying in Retirement
Pros
Housing costs are fixed if you have a fixed-rate mortgage or have paid for your mortgage.
You can build equity and wealth from the value appreciation of your property.
You may receive tax deductions on your mortgage interest and property taxes.
You will have the ability to make modifications to your home as you see fit.
You will feel secure and at ease in your own surroundings and community.
Cons
Maintenance & repairs will be your responsibility.
Insurance & property taxes can be more expensive than expected.
Your wealth will be tied up in one less liquid asset.
If you need to move, selling a home is time-consuming and costly.
As you age, physical upkeep of the property may become challenging.
Pros and Cons of Renting in Retirement
What if you choose to rent a home during retirement instead of buying? Here are the benefits and disadvantages worth considering.
Pros
Maintenance is never a headache or a financial blow because of repairs.
You have the ability to relocate freely when your needs change
Your money will always be liquid and available for other things.
You will know exactly what your housing will cost annually (except annual rent increases).
Cons
Rent can go up every year, which makes budgeting difficult when you have the right amount you are paying every month.
You will never build equity or wealth while you rent.
If you rent and do not pay your rent, the landlord may proceed with the process of eviction.
There are many restrictions placed upon renters by landlords concerning changes made to their rental units.
Renting and buying can provide two different benefits, which are based on your needs and preferences. If you value having a stable place to live with the ability to customize it as you see fit, then owning a home is likely the best option for you.
If you value having the flexibility to move at any time without being tied down to a mortgage and prefer to avoid maintenance costs, then renting is likely the best option for you.
Understanding local housing options helps an Arlington property manager advise on whether to rent or buy in retirement.
Financial Planning Tips for a Comfortable Retirement Lifestyle
Smart financial planning is important to help your retirement years be comfortable and low-stress. The following will give you some ideas on how you can connect your housing decisions with the long-term financial picture.
1. Create a Realistic Retirement Budget
Determine what your retirement income will be by listing all of your expected income sources, then calculate what you expect to spend on housing, medical care, utility bills, groceries, and other items that you may want or need.
Creating a budget for your retirement will allow you to see if the housing you plan to purchase is affordable in the long run and will not require significant cutbacks in your standard of living as you age.
2. Factor in Healthcare and Long-Term Care
Medical costs are very likely to increase as we age. Review Medicare coverage and research possible supplemental insurance options. Assess whether your current home will meet your future mobility needs or determine what modifications may be required. Preparing for these expenses today reduces potential financial burdens that may occur when your health changes in ways you do not anticipate.
3. Pay Down Debt Before Retiring
Carrying a mortgage payment, a car loan, or credit cards into retirement significantly impacts your ability to cover essential expenses from a fixed income. The best time to pay down debt is while you are employed. Paying off debt on a regular basis creates more freedom to choose where you live and less financial burden when unforeseen expenses arise. For retirees or those approaching retirement who are managing significant unsecured debt, exploring Freedom Debt Relief programs may be another option to consider when developing a strategy for reducing financial obligations
4. Consider Downsizing Strategically
Generally, a smaller house is going to have lower monthly utilities, property taxes, and maintenance costs. When you sell your family home, it will also provide money for you to retire on by using the equity from the sale of your home. If you are planning to keep the home in question, then hiring an experienced property manager may be the way to go.
5. Build a Professional Advisory Team
Before you decide on your housing options, consult with a financial planner to run all possible scenarios. A tax professional will explain how selling versus renting out your home may impact your taxes. Reviewing local market insights from a realtor and property manager can help you avoid costly mistakes and ensure that you are maximizing your retirement resources.
Conclusion
The decision to live in a retirement home will have a lasting impact on your day-to-day life as well as your financial situation. By considering where you want to live (location), how much maintenance is involved with your home, and how much it will cost, then by making a decision regarding rent or purchasing, you will be able to make an informed decision.
If you plan to buy a house for retirement, ensure to partner with a local property manager. These professionals understand both the legal requirements and operational necessities to make the home comfortable and even profitable, if you choose to rent.
Guest Post - Things to Consider While Preparing for A Bathroom Renovation
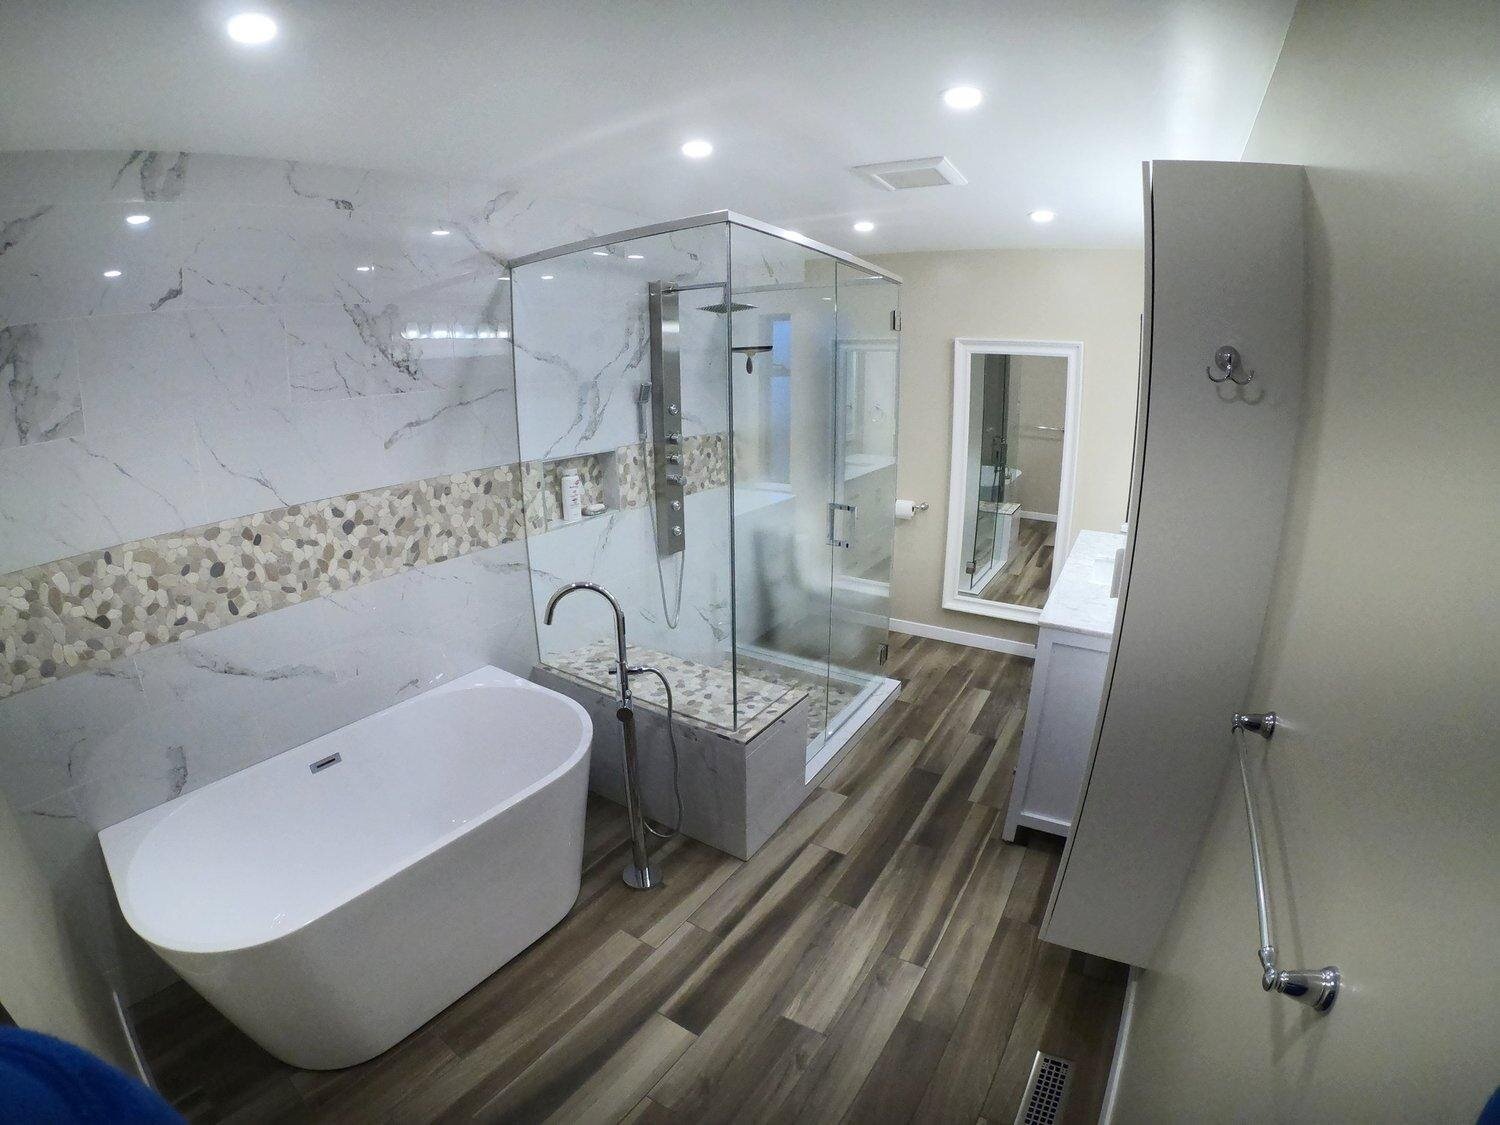
Renovating a bathroom is both an exciting and rewarding experience. A remodeled bathroom reflects personal style and delivers the desired comfort, maximum functionality, and added value. But to get the outcome you dreamt of requires time and a considerable amount of investment. Lack of focus and proper planning can get it off-track in no time. At times it gets overwhelming and daunting for homeowners as there is a lot of decision-making involved, and the bathroom is an essential everyday space that you can’t keep disorderly for long.
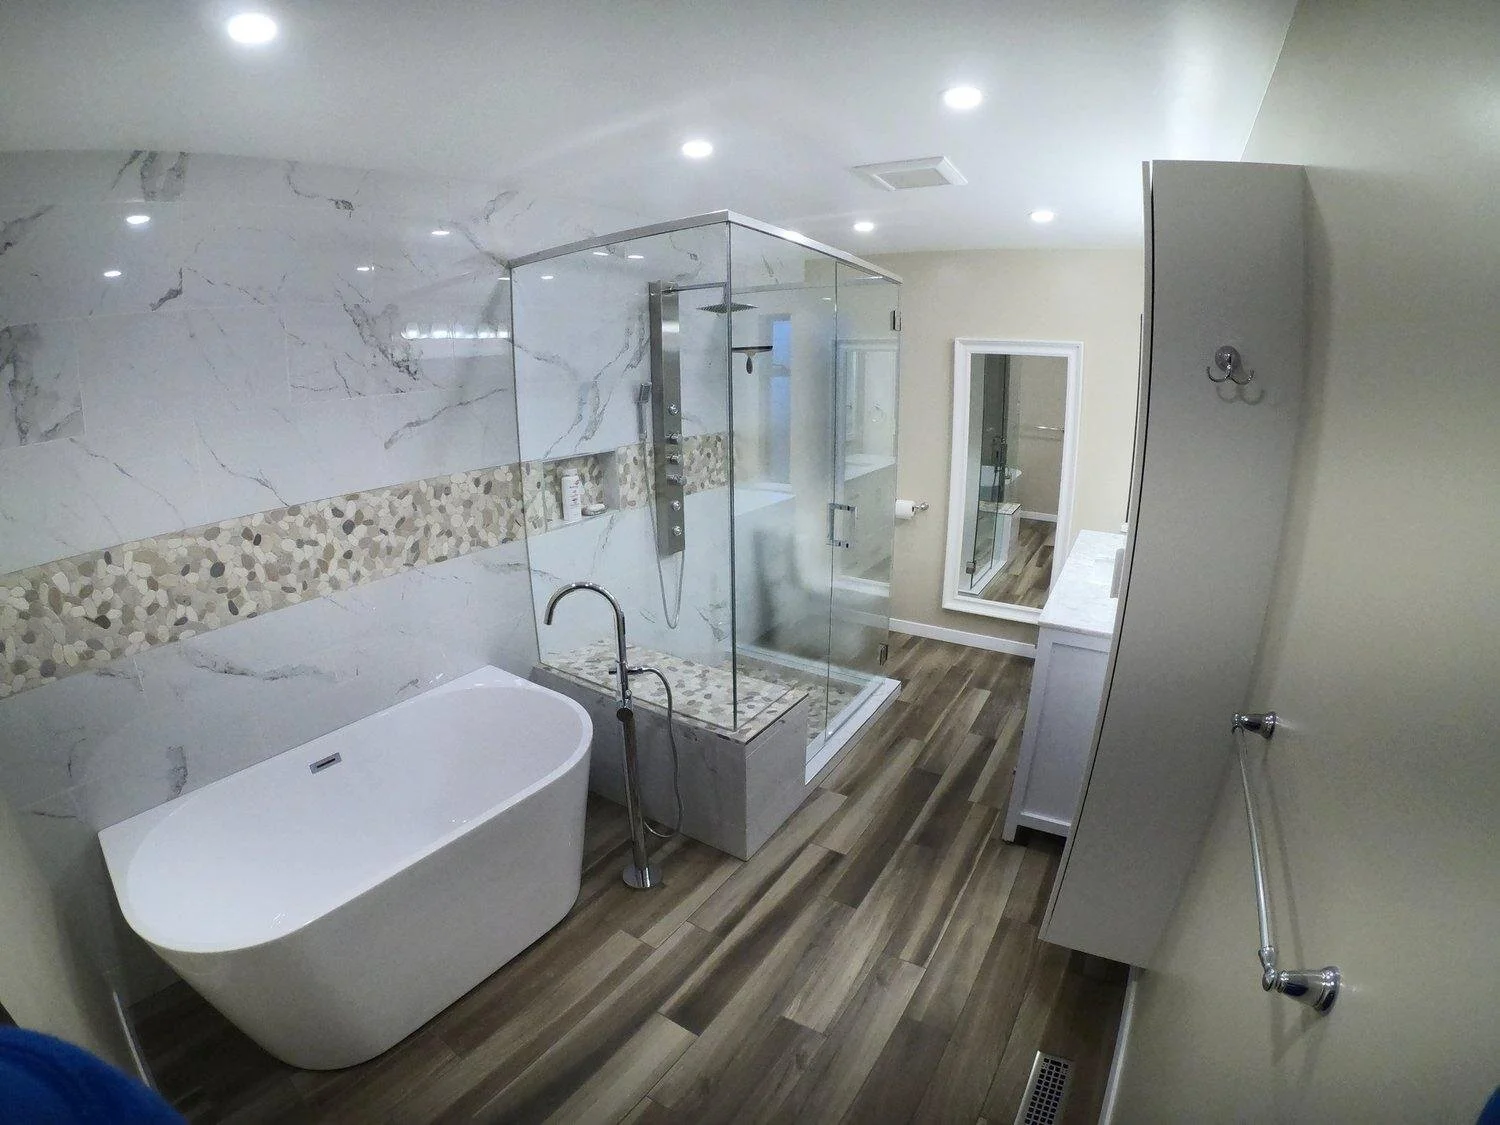
Renovating a bathroom is both an exciting and rewarding experience. A remodeled bathroom reflects personal style and delivers the desired comfort, maximum functionality, and added value. But to get the outcome you dreamt of requires time and a considerable amount of investment. Lack of focus and proper planning can get it off-track in no time. At times it gets overwhelming and daunting for homeowners as there is a lot of decision-making involved, and the bathroom is an essential everyday space that you can’t keep disorderly for long.
If you are prepping up for a bathroom renovation, carefully considering a range of factors and a little advanced preparation and foresight can ensure that the project does not upend your life or create needless hassles. For people undertaking a bathroom renovation project for the first time, doing a thorough research and taking expert assistance will be a prudent choice.
Consider the following things before demolishing the bathroom to enjoy a smooth bathroom renovation process from conceptualizing to completion:
Plan it
Planning is the best way to start a bathroom renovation project. Write down your list of priorities, matters with the present bathroom, the expectations, or what you wish to achieve at the end of the project. Setting clear goals and creating a well-defined plan is the key to a successful bathroom renovation.
Set a budget
There is no defined cost of renovating a bathroom. You can spend as much as you wish, and for this reason, setting a budget is critical. Do your research keeping all the required changes, like adding a new sink, a fresh coat of paint, lighting and plumbing fixtures, and cabinets in mind to get an idea of your ability and willingness to spend on different aspects. Setting a budget and defining the financial limits will make it easier to decide on the layout, design, and other features.
Layout
Keeping the current layout is always cost-effective. But if you have the budget and are not happy with the present bathroom condition, you can redesign it from scratch to suit your needs. Keep in mind that completely changing the layout will also mean plumbing alterations to accommodate the renovations. Don’t only think about the present while planning the layout. Plan it with the future in mind to accommodate all the changes you foresee in the coming times.
Look for design inspirations
Browse through the internet or hire an architect to know ways to get the best out of the available space. A bathroom design should incorporate both aesthetics and functionality. Include factors like color, shower, bathtub, tiles, faucets, and fixtures while planning the bathroom design. Avoid experimenting too much with the materials and colors and keep things consistent with the rest of the house. While designing, also factor in how it will affect the resale ability of the house.
Keep the space in mind
Having an exceptional bathroom design idea is not enough. There should also be adequate space to execute it properly. Avoid setting unrealistic expectations and try to manage available space optimally.
Appropriate plumbing fixtures and features
Plumbing faucets, fixtures, and hardware are inseparable elements of a bathroom renovation. They have a considerable impact on the overall appearance. Choose hardware that fits the budget and fulfills the family’s needs. It is surprising how things like drawer pulls or door handles can transform the look of your bathroom. You can also opt for greener alternatives while upgrading the bathroom features. For example, consider a low-flow toilet, energy-efficient water heater, and no-VOC paints.
Plan the storage
Storage is a crucial part of any bathroom. Planning cabinets, shelves, and other solutions can get tricky. The storage space should be functional, easily accessible, must accommodate all your stuff, and look aesthetically pleasing at the same time.
Pick the right materials
Only once you enter the world of bathroom renovation, you realize that there are much more details to look into than you thought. The choice of materials for different bathroom accessories depends on your need and the bathroom style. Do proper research before choosing a durable material for the countertops, floor tiles, cabinets, bathtub, backsplash, and lighting.
Lighting
It is easy to forget about lighting while remodeling a bathroom. Bad lighting can destroy the look of the space. Consider maximizing the natural lighting through a window or skylight, and add attractive lighting fixtures and recessed LEDs to perfectly light it up.
Adequate ventilation
Bathrooms require excellent ventilation owing to their susceptibility to dampness. Careful planning is essential to finalize the modes of ventilation (window vents, exhaust fans) and their positioning to maximize airflow.
Hire professionals
Selecting a reliable remodeler is essential to bring your renovation ideas to life. Avoid giving in to the temptation of hiring the one that offers the lowest price. Evaluate them for their skills, expertise, commitment, and reliability.
Taking all the above factors into account while planning a bathroom renovation will save both time and money. All the disturbances and disruptions during the process are temporary, and the final result will surely be worth all the efforts.
About the author:
Richa has over 10 years of content writing experience with leading home improvement and renovation companies. This article is written by her for SITL Home Renovation and Design - Greenwich, CT renovation experts.